 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Figure Heloc
 Hyperliquid
 Dogecoin
 USDS
 Rain
 LEO Token
 Wrapped stETH
 Zcash
 WhiteBIT Coin
 Wrapped Bitcoin
 Cardano
 Binance Bridged USDT (BNB Smart Chain)
 Stellar
 Wrapped Beacon ETH
 Monero
 Chainlink
 Canton
 Wrapped eETH
 Bitcoin Cash
 Dai
 sUSDS
 USD1
 Ethena USDe
 Gram (prev. Toncoin)
 Coinbase Wrapped BTC
 Litecoin
 Global Dollar
 Circle USYC
 WETH
 Hedera
 Sui
 PayPal USD
 USDT0
 Avalanche
 Cronos
 Tether Gold
 Shiba Inu
 NEAR Protocol
 BlackRock USD Institutional Digital Liquidity Fund
 Ondo US Dollar Yield
 Ethena Staked USDe
 Uniswap
 Bittensor
 World Liberty Financial
 PAX Gold
 MemeCore
 Aster
 HTX DAO
 OKB
 Ripple USD
 Ondo
 Little Pepe
 USDD
 syrupUSDC
 Falcon USD
 Polkadot
 Morpho
 Mantle
 DeXe
 Aave
 BFUSD
 Worldcoin
 Sky
 Internet Computer
 Bitget Token
 Pi Network
 Ethereum Classic
 Pepe
 United Stables
 Jupiter Perpetuals Liquidity Provider Token
 Spiko EU T-Bills Money Market Fund
 Blockchain Capital
 Quant
 KuCoin
 Janus Henderson Anemoy Treasury Fund
 Jito Staked SOL
 USDGO
 Stable
 Kelp DAO Restaked ETH
 Invesco Short Duration US Government Securities Fund
 JUST
 Binance-Peg WETH
 POL (ex-MATIC)
 Rocket Pool ETH
 Cosmos Hub
 Kaspa
 Binance Bridged USDC (BNB Smart Chain)
 Render
 Algorand
 Wrapped BNB
 ADI
 Function FBTC
 Beldex
 USDtb
 NEXO
 Jupiter
 LAB
 syrupUSDT
 Spiko Amundi Overnight Swap Fund (EUR)
 币安人生 (BinanceLife)
 Gate
 Binance Staked SOL
 Ethena
 Audiera
 Janus Henderson Anemoy AAA CLO Fund
 Filecoin
 GHO
 Pump.fun
 NEW X CEO IS BACK
 Polygon Bridged USDC (Polygon PoS)
 Lighter
 Solv Protocol BTC
 Flare
 Lombard Staked BTC
 Usual USD
 XDC Network
 YLDS
 clBTC
 Midnight
 Provenance Blockchain
 USX
 Aptos
 Aerodrome Finance
 Venice Token
 StakeWise Staked ETH
 TrueUSD
 Arbitrum
 Kinetiq Staked HYPE
 A7A5
 tBTC
 Injective
 PancakeSwap
 Dash
 EURC
 VeChain
 Ondo Short-Term U.S. Government Bond Fund
 Pudgy Penguins
 c8ntinuum
 Hastra PRIME
 Mantle Staked Ether
 Official Trump
 Celestia
 Polygon PoS Bridged DAI (Polygon POS)
 Ether.fi
 Resolv wstUSR
 Artificial Superintelligence Alliance
 COCA
 Sun Token
 Bonk
 SPX6900
 Doge Strategy
 Liquid Staked ETH
 First Digital USD
 Arbitrum Bridged WBTC (Arbitrum One)
 LayerZero
 Virtuals Protocol
 Pyth Network
 The9bit
 Terra Luna Classic
 Wrapped Flare
 Kinesis Gold
 Sei
 L2 Standard Bridged WETH (Base)
 apxUSD
 Steakhouse USDC Morpho Vault
 Curve DAO
 Stacks
 Jito
 Monad
 Kite
 Binance-Peg XRP
 Gnosis
 Ether.Fi Liquid ETH
 Tezos
 Renzo Restaked ETH
 Lido DAO
 MegaUSD
 Noon
 Royal Dollar
 sBTC
 AINFT
 BitTorrent
 Bitcoin SV
 Jupiter Staked SOL
 Pendle
 Savings USDD
 Olympus
 DoubleZero
 Plasma
 Marinade Staked SOL
 Legacy Frax Dollar

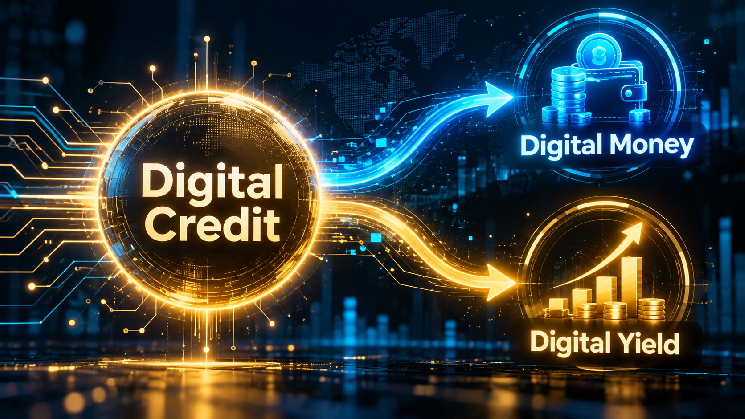
The new business model of building on top of digital credit to create digital money and digital yield can be roughly categorized into two different architectures.
- Debt-based, tranching structures
- Full-reserve, spendable balance structures
This article gives a general overview of these models, with an analysis of economic implications.
Digital Credit, Digital Money and Digital Yield
To get started, I will define these terms. Digital Credit is the credit-like instruments issued by corporations with large Bitcoin balance sheets. Today they are five Nasdaq-listed perpetual preferred equity—STRC, SATA, STRK, STRF, STRD—and all five are the top five most liquid preferred equity securities in the United States. Digital Credit is L2 because it is built on top of Bitcoin, which is L1.
Digital Money and Digital Yield are the L3 products that could be built on top of Digital Credit.
Now obviously, Bitcoin is Digital Money. In this article I am using the terms popularized by Michael Saylor in corporate bitcoin discourse to describe the economic ecosystem that is emerging on top of public company issuance of Bitcoin-linked securities.
Under that paradigm, Digital Money refers to something that holds a very stable fiat-denominated value that is built on top of Digital Credit. And Digital Yield refers to something that concentrates and amplifies the yield of Digital Credit. Both Digital Money and Digital Yield are L3, since they exist on top of L2 Digital Credit.
Now that we know Digital Money and Digital Yield, we will move on to the different architectures for them.
Debt based tranching
The first and primary one is a debt-based tranching structure in which the digital credit is used as the base collateral asset. The junior tranche is effectively leveraged long digital credit, and the senior tranche is effectively principal protected via the junior tranche’s permanent capital. Right now this is by far the most common structure because we see quite a lot of AUM inside these types of systems. For example, Saturn is a tokenized protocol that holds a lot of STRC, and the financial engineering built on top of Saturn is Strata, which uses the same tranching approach (the name “Strata” likely refers to stratifying the different financial layers within the setup).
Another very important example is UTXO Management’s Preferred Income Strategies LP. This is a dual-class fund: a junior fund share class and a senior fund share class. The juniors are effectively leveraged long the underlying digital credit portfolio and the seniors receive a highly principal-protected 7.5% annual yield. Now, the caveat is the portfolio value cannot fall below the invested capital representing the senior’s original principal. Seniors must get all their principal back before the juniors can get paid. UTXO is able to run some other alpha-generating strategies which may reduce downside risk of the digital credit portfolio or employ relative value trades to capture market mismatches. Such actions increase the returns of the total portfolio. And since the juniors are leveraged long this portfolio, they have the potential to outperform. Meanwhile, the seniors have the entire principal protection cushion. Tranching using the two share classes therefore matches different parties’ risk preferences and desires for total return in a way that services both investor profiles.
You might notice that this basic structure is quite similar to what a digital credit issuer like Strategy or Strive does with their own capital structure. If the issuer raises capital using preferred equity or debt, they have created a more senior layer—that becomes the principal protected layer, albeit it is asset value coverage rather than encumbered, callable protection—while the common equity becomes the junior tranche that is effectively leveraged beyond the underlying asset. In other words, the digital yield and digital money products built on top of digital credit using this tranching structure is a higher order retelling of the same digital credit and digital capital maneuvering done one layer below.
Now, it’s important to realize that any kind of leveraged system that borrows money and then invests the borrowed money into digital credit, is effectively engaging in the Layer 3 methodology of tranching, because that person is now leveraged long, and his counterparty is another person who becomes principal protected. Outside of raw asset coverage ratios, the specific degree of principal protection depends on whether the collateral asset—in this case the digital credit instrument—is sitting in some kind of custody that can be enforced.
Put differently, should the digital credit position go underwater, the creditor is able to possess the assets, liquidate the collateral, and be made whole. Enforceability depends on the exact parameters of these structures. Within the case of something like Strata, it is enforced by a blockchain consensus dependent smart contract. The successful execution of that smart contract is where the trust resides. Within the UTXO Preferred Income Fund, you have an enforceable structure within the confines of a regulated hedge fund that all LPs partake in.
One key insight is that such a debt-based structure is far broader and more general than one might initially suspect. Let’s say somebody takes out a mortgage against their house and buys digital credit with it. They have somewhat created that L3 concept because money is being created via the traditional fractional reserve banking process, and collateral has been encumbered. Now, in this case, digital credit isn’t exactly the collateral because the house is the collateral. However, the entire economic setup would not be possible without the presence of digital credit serving as an investable asset and a location to deploy borrowed capital. In a sense, there is a bit of a shadow banking condition that emerges if a widespread group of people take out loans of various forms that might be secured by other assets or even unsecured, and then use the borrowed capital to invest in digital credit in order to be leveraged long digital credit.
The assets that emerge out of this type of behavior is basically conventional credit. It is not tokenized, and there is nothing special about it. It takes the form of an asset-backed security, and frankly, you wouldn’t even know that digital credit was on the other side of it most of the time. And for this reason, it’s not completely precise to call it the L3 digital yield concept, because it does not deal directly with digital credit. At the same time, it is a meaningful market mechanism which may emerge, and we should actively monitor the emergence of this behavior as digital credit scales.
Now I will go into the potential problems and current shortfalls of this type of debt-based, tranching method. The most obvious one is that there is no backstop besides the debtors’ own balance sheets and there is a constant need for debtors to take the leveraged long side for this to work. This is a persistent issue that caps the scalability of L3 digital money and digital yield solutions. If it is the case that you always need a leveraged long party in order to create the principal protection for the senior tranche, then you become constrained by the availability of leveraged long parties. First, there may be much better things to be leveraged long, so you might not have junior capital if there are more compelling opportunities out there. Second, there is always a push-pull relationship between the seniors and the juniors. Because the entire thing exists within a tranche structure, the total portfolio is a zero-sum game. Whatever the seniors gain, the juniors must lose, and vice versa. And because of this, the seniors can only demand yield up to a certain level before the juniors leave. Concurrently, the juniors must receive a return at least to a certain level before they would be willing to take the risk. This relationship needs to reach an equilibrium clearing price. But even at that clearing price, it is doubtful that there will be enough demand for leveraged long digital credit to persistently create the senior principal protected position.
This exact challenge is supported by the anecdotes of the tranching structures I am aware of: there appears to be a relative shortage of folks willing to be juniors and a relative surplus of folks willing to be seniors.
Now, the way the fiat system solves this problem actually presents a very interesting case study for L3’s current shortcomings. You see, fiat solves this problem by having an elastic public balance sheet behind the private credit system. Commercial banks can create credit and deposit money, while the central bank supplies the ultimate settlement asset (which is often called: M0, base money, or bank reserves). When systemwide deleveraging threatens the monetary system, the central bank can create reserves and replace disappearing private liquidity, while the Treasury, deposit insurer, or other public institutions can absorb or redistribute credit losses where policymakers choose to do so. This means the fiat system does not require a private actor to remain willing to be the marginal leveraged long investor during a panic: the public sector can temporarily take that role and prevent forced deleveraging. Thus fiat money can remain present even when the leverage behind it disappears. (Digital Money implemented via the tranching architecture cannot do this.)
Equity and creditors can still be wiped out in fiat. But the distinctive feature of fiat is that there is no hard nominal constraint on the public sector’s ability to manufacture the settlement asset needed to stabilize the financial system. The ultimate macroeconomic constraint on sustained use of that capacity is the availability of real resources and the ability for individuals to tolerate the inflationary impact of such currency debasement. This is the true limit of fiat’s debt-based system at a societal level; and indeed this is also the core conclusion of Modern Monetary Theory.
Now, it should be easy to see that digital credit does not have this type of backing today. It is doubtful that any central bank today would consider buying digital credit when it is underwater to make investors whole (even though central banks do this often with traditional forms of credit like mortgages and other bank loans). And so in that sense, the concept of a fiat-banking-like system that is constructed on top of digital credit to serve as widespread L3 digital money is dubious at best within the next few years. Certain things need to happen—the main one being better Basel risk weights for Bitcoin—and even then meaningful progress would likely be quite slow.
Lacking the support of the commercial banking system or the central banking system, the only capital that can come in as the leveraged Digital Yield juniors to support the creation of the Digital Money seniors is private capital willing to take the risk.
Full reserve, spendable balance
This now brings us to the second form of L3 digital money. These are full-reserve, spendable balances. (A quick disclaimer here is that just because this one is “full reserve” does not imply that the tranching structure is “fractional reserve”. Full reserve just means that the available spendable balance is fully supported by unencumbered shares held on the spot.)
This concept is to combine digital credit with a basket of other credit instruments to create a composite benchmark that is both highly liquid and yields over the risk-free rate (here the risk-free rate just means the short-term U.S. T-bill rate). And if this asset also had daily liquidity and could accrue interest on a daily basis, then you have what is like a money market fund with added risk premium and volatility. If this thing could then be tokenized or turned into a spendable balance, then you now have what could be considered a digital currency that pays higher yield. Note that the composite benchmark is not required: one could have only digital credit in the balance and make it spendable too. Since the volatility of digital credit is higher than short duration credit instruments like FLOT or FLTR (floating rate note ETFs) or JAAA or CLOA (AAA-rated CLO tranches), purely digital credit will be a more volatile albeit higher yielding spendable balance.
The real hurdle for this concept is regulatory acceptance. Consider the recent plight over stablecoins and the Clarity Act, and how banks rejected Clarity because stablecoins serve as a big competitor to them. One of the most contentious issues was stablecoins paying yield, which would compete with traditional bank deposits. Now if we had a spendable balance with relatively stable par value that pays a higher-than-risk-free yield due to a credit risk premium, then this would probably create even more of an issue. In that sense, the idea of using relatively-stable-value securities (of which digital credit is just one group) as spendable balances is something that is sensitive when considering the different parties that need to be satisfied for this to become legally possible.
A softer version of the spendable balance concept is something like Castle: businesses can hold reserves in STRC, liquidate STRC into cash on demand, and then use that cash for operating expenses. The conversion follows normal securities T+1 settlement. This is like a brokerage account connected to a payment provider. Neither the shares nor representation of the shares (like a token) are being transferred to the final recipient of the payment.
Of course, there are far less obstacles to creating a simple fund that holds digital credit without making the fund interests peer-to-peer transferable. OranjeBTC has done exactly this with their Digital Credit ETF launched in Brazil. In this specific case, OranjeBTC has even employed a currency hedge procedure to deliver yields denominated in Brazilian Real. Even though this return stream can probably be replicated without much difficulty, it is nevertheless far more convenient for most people to buy a single ticker that takes care of everything.
Conclusion
The existing developments and current regulatory parameters suggest that the debt-based tranching solution will likely be more of the activity within the L3 field. There are several different variations of both archetypes: within this article we’ve gone through a few different versions.
I aim to explore such models—existing and theoretical—in greater depth in the future. Stay tuned.
Disclaimer: This content was prepared on behalf of Bitcoin For Corporations for informational purposes only. It reflects the author’s own analysis and opinion and should not be relied upon as investment advice. Nothing in this article constitutes an offer, invitation, or solicitation to purchase, sell, or subscribe for any security or financial product.
This post Understanding Digital Money and Digital Yield first appeared on Bitcoin Magazine and is written by Allard Peng.
